Minimalism’s Hidden Power: Why Less Brings More

You’ve been drowning in stuff for years. Maybe it started small, a few extra purchases here and there. Now you’re surrounded by things you don’t use, don’t remember buying, and honestly, don’t even like anymore.

You’re not alone, and the benefits of minimalism lifestyle go far beyond just having a cleaner house. We’re talking about real, measurable shifts in your finances, your time, and your mental state.

The research here is compelling. According to a UCLA study on families and clutter, stress levels spike alongside the sheer volume of household objects. The constant visual noise of our possessions keeps our brains in a state of low-grade, chronic distraction.

But here’s the good news: you don’t need to live in an empty white room to reap the rewards. Let’s break down what actually happens when you decide to own less.

What Minimalism Actually Means (And What It Doesn’t)

Let’s clear up the biggest misconception right now. Minimalism isn’t about owning as little as possible. It’s not a competition to see who can fit their life into one suitcase.

It’s not about living in a sterile, empty space that looks like a furniture showroom.

Minimalism is about removing friction. It’s about clearing away the things that drain your energy, your money, and your attention so you have more room for what genuinely matters to you.

So what does that look like in practice? It looks different for everyone. For one person, it might mean cutting their wardrobe down to 30 versatile pieces.

For another, it might mean keeping a large library but getting rid of all the duplicate kitchen gadgets they never touch.

Here’s the key distinction: minimalism sits on a spectrum, not a strict rulebook. There’s no “right” number of items to own. There’s only the number that feels manageable and supportive to you.

You might hear people use “minimalism,” “simple living,” and “frugality” interchangeably. They’re related, but they’re not the same thing. Frugality is about spending less money.

Simple living is about slowing down and reducing commitments. Minimalism specifically focuses on reducing physical and mental clutter.

You can be a minimalist who spends generously on the things they love. In fact, that’s the goal. You’re not depriving yourself.

You’re being more selective.

That’s the mental reframe that makes all the difference. You’re not losing things. You’re gaining space.

The Financial Payoff: What Happens to Your Money

The financial benefits of minimalism might be the most tangible reason to start. And they kick in faster than you’d expect.

Here’s what our research consistently shows: when people declutter their homes, their spending habits change naturally. You start to see your past purchases for what they are, a pile of money converted into things you didn’t truly need. That awareness makes you pause before the next impulse buy.

Let’s break down the actual financial impact:

  • No more duplicates. How many phone chargers, scissors, or bottles of half-used cleaner do you own? Decluttering reveals the duplicates, and you stop buying them.
  • Fewer “storage solution” purchases. We spend a fortune on bins, baskets, and organizers. Those are costs that vanish entirely when there’s less stuff to organize.
  • The selling bonus. Selling your gently used items on resale platforms can generate real cash. It’s not retirement money, but a few hundred dollars from stuff you’d forgotten about feels like found money.
  • The maintenance drop. Fewer things mean fewer repairs, fewer replacements, and less money spent keeping everything running.

When we talk about monthly savings, the numbers vary. But a consistent pattern emerges from aggregate buyer feedback. People who deliberately simplify their possessions report saving anywhere from $200 to $500 per month in their first year.

That’s not because they’ve become extreme couponers. It’s simply because they’ve stopped the constant, low-level purchasing that most of us do on autopilot.

The shift is psychological as much as practical. Once you understand the connection between what you own and what you spent to get it, shopping stops being a hobby and starts being a transaction you evaluate carefully.

The Time Dividend: Hours You Get Back Every Week

Money is easy to measure. Time is where minimalism gets even more interesting.

Think about how much time you spend managing your stuff. Maybe you’re searching for your keys every morning. Maybe you’re shuffling through a closet full of clothes to find the three outfits you actually wear.

Maybe you’re reorganizing a drawer that somehow keeps getting messy.

It adds up faster than you think.

  • The search factor. On average, people report spending 10 to 15 minutes a day looking for misplaced items. That’s over 60 hours a year.
  • Cleaning speed. Clutter makes cleaning slower. You have to move things around just to dust or vacuum. A clear space takes half the time to maintain.
  • Decision fatigue. Every glance at a cluttered surface triggers your brain to process multiple decisions. Should I put that away? Where does it go? Do I still need it? Eliminating these micro-decisions frees up serious mental energy.

Our research suggests that decluttering saves the average person around 45 minutes per day once the initial purge is complete. That’s nearly five hours a week.

Here’s a quick comparison of how a typical morning changes:

Task Before Decluttering After Decluttering
Finding clothes 10–15 minutes of shuffling 2 minutes, everything fits and matches
Finding keys/phone 5–10 minutes of searching 30 seconds, designated spot
Making coffee Digging through crowded cabinets Everything visible, grab and go
Getting out the door Feeling rushed and frazzled Leaving calm and on time

The morning routine alone goes from a stressful scramble to a smooth, quiet process. That’s not a small quality-of-life upgrade. That’s a fundamental shift in how your day starts.

Mental Clarity and Emotional Relief: The Psychological Shift

This is the benefit people talk about the most, and it’s also the hardest to explain until you’ve experienced it. But the research is clear: visual clutter has a direct impact on your brain.


Your brain processes everything in your field of vision. When it sees a messy desk or a cluttered floor, it silently registers all of that as “unfinished business.” These are open loops that pull at your attention, even when you’re not consciously aware of them.

Princeton University researchers confirmed this link. They found that physical clutter competes for your attention, reducing your ability to focus on a single task. The more stuff you see, the harder your brain has to work to ignore it.

Here’s what clearing that visual noise does for you:

  • Focus improves. With fewer distractions pulling at your peripheral vision, you can actually concentrate on what you’re doing.
  • Anxiety lowers. Your home becomes a “non-demand” space. It doesn’t ask anything of you when you walk in the door. That’s a rare and valuable quality in a living space.
  • You stop comparing. When your life isn’t tied up in physical possessions, you stop measuring your success against other people’s stuff.

There’s a quieter benefit too. You start to appreciate what you actually own. With fewer things, each item becomes more visible and more valued.

A well-chosen book or a favorite piece of furniture gets the attention it deserves.

The psychological shift isn’t instant. It takes time for your brain to adjust to the new, calmer environment. But after a few weeks, most people report a distinct sense of relief.

The background hum of “there’s too much here” finally goes quiet.

The Transition: What the First 30 Days Really Look Like
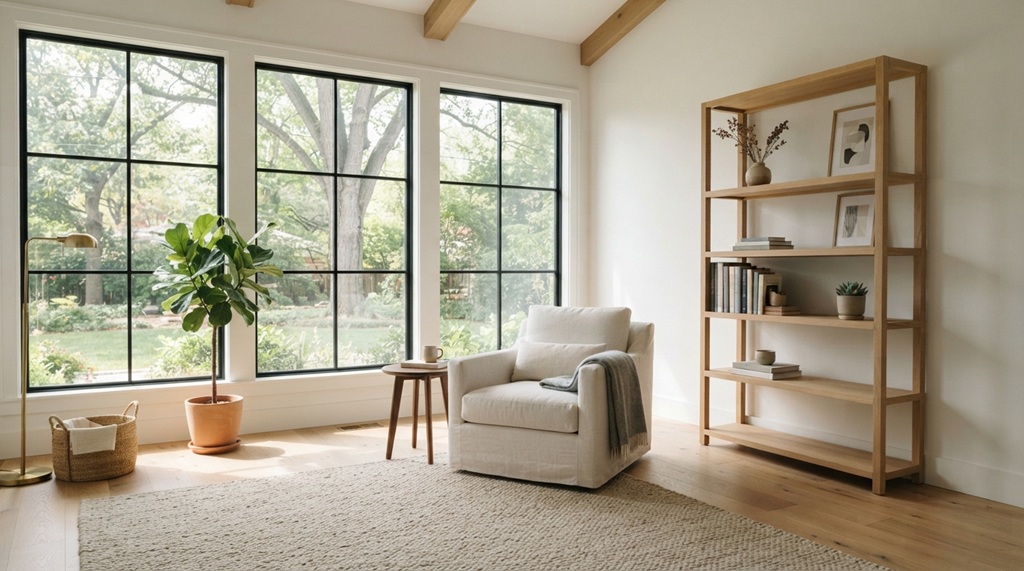
An open bright room with a neutral armchair and a sparsely filled bookshelf.


Let’s be honest about something. The first few weeks of decluttering are not fun. They’re emotionally exhausting in ways you might not expect.

You’ll feel regret about money you wasted. You’ll argue with yourself over whether you might need something “someday.” You might even feel a sense of grief as you let go of items tied to past versions of yourself.

This is normal. And it’s temporary.

Here’s what the first 30 days realistically look like, based on our research and pattern analysis:

Week 1: The Overwhelm Phase

You’re enthusiastic. You start with a closet or a drawer and immediately feel overwhelmed by the sheer volume. You make progress, but it feels slow.

Expect fatigue and some second-guessing.

Week 2: The Decision Phase

The obvious trash is gone. Now you’re hitting the hard stuff, the gifts, the “someday” items, the things with sentimental weight. This is where most people stall.

Push through it. The one-year rule helps here: if you haven’t touched it in a year, you probably won’t.

Week 3: The Momentum Phase

Something clicks. You start seeing empty shelves and clear surfaces. The visual results become motivating in themselves.

This is where the process actually starts to feel good.

Week 4: The Integration Phase

You’re not just purging anymore. You’re organizing what’s left. You’re developing systems for the things you genuinely use and love.

This is when the new normal starts to take shape.

The biggest mistake people make is trying to do everything in one weekend. That’s a recipe for burnout. Instead, work in focused sessions of 30 to 60 minutes.

Handle one category at a time: clothes, then books, then kitchen, then paperwork.

Remember that family members might not share your enthusiasm. They might feel threatened or judged by your decluttering. Be gentle.

Lead by example rather than by sermon. Let your calm satisfaction be the argument, not your words.

The transition period typically lasts two to three months before your new habits feel natural. As of 2026, the growing body of research on behavioral change suggests that timeframes vary widely, but the core principle holds: consistency beats intensity.
Mortgage Pre-Approval: What It Is & Why It Matters

The exact phrase “what is a mortgage pre approval” gets Googled tens of thousands of times every month. Most people searching it have never bought a home before. They’re scared their credit isn’t good enough, or they’re worried they’ll look stupid asking a lender basic questions.

Neither is true.

A mortgage pre-approval is simply a lender’s written commitment stating how much they’re willing to lend you, based on verified financial documents. Under the Truth in Lending Act (TILA), lenders must provide standardized disclosures, and a Loan Estimate arrives within three business days of your complete application. That document spells out your interest rate, monthly payment, and closing costs in plain numbers.

Let’s walk through exactly what this process involves, because the details matter more than most first-time buyers realize.

Quick Answer

A mortgage pre-approval is a lender’s conditional commitment to lend you a specific amount. It comes after they verify your income, assets, employment, and credit. It differs from pre-qualification, which is a rough estimate.

A pre-approval letter lasts 60 to 90 days and carries real weight with sellers.

Why Mortgage Pre-Approval Matters (And What It Actually Is)

Here’s the reality: a pre-approval is not a loan guarantee. It’s a conditional promise based on your current financial picture. The lender reviews your tax returns, pay stubs, bank statements, and credit report.

They verify your debt-to-income ratio (DTI) and decide you’re a reasonable lending risk.

The distinction between pre-approval and pre-qualification trips people up constantly. A pre-qualification is a conversation. You tell the lender your income and debts, they estimate what you might afford.

No documents. No credit pull. No verification.

Sellers see that letter for what it is, a warm fuzzy statement with no financial backing.

A pre-approval, meanwhile, means the lender has actually pulled your credit and reviewed your paperwork. They ran your numbers through their underwriting guidelines. If the seller accepts your offer, the lender has already verified most of what they need to fund your loan.

How Pre-Approval Differs From Pre-Qualification

Speaking plainly, a pre-approval is the only one that matters in a competitive housing market. Real estate agents will tell you that listings in desirable areas receive multiple offers within days. A buyer who shows up with only a pre-qualification letter often gets passed over.

The lender’s verification during pre-approval covers several key areas. They check your employment history, usually the past two years. They review your W-2s and tax returns to confirm your income is steady.

They examine your bank statements for large deposits that need explanations. They pull your credit report to assess how you handle debt.

What a Lender Actually Verifies

Your credit score matters, but it’s not the only number. Lenders calculate your debt-to-income ratio by dividing your monthly debt payments by your gross monthly income. As of 2026, most conventional lenders want your DTI at 43% or lower, though some programs allow up to 50%.

Your assets also get scrutinized. The lender wants to confirm you have enough cash for the down payment and closing costs. If a family member gifts you money, they’ll need a signed gift letter explaining the funds aren’t a loan.

Irregular deposits without documentation can delay your approval significantly.

How the Pre-Approval Process Works Step by Step

Getting pre-approved takes less time than most people expect. Once you’ve gathered your documents, many lenders can issue a decision within 24 to 72 hours. Here’s the workflow:

Step 1: Choose a lender. You can work with a national bank, a local credit union, or a mortgage broker. Each has different strengths. Local lenders often provide more personalized service.

Online lenders might offer faster timelines. A broker can shop your file across multiple lenders to find the best rate.

Step 2: Submit your application. Most lenders offer online applications these days. You’ll enter your personal information, employment details, and financial data. This is the 1003 form, standard across the industry.

Step 3: Provide documentation. The lender needs to verify everything you claimed. Expect to upload or deliver the documents listed below.

Step 4: Authorize a credit pull. The lender does a hard inquiry on your credit report. This typically drops your score by a few points temporarily.

Step 5: Underwriting review. The loan officer or underwriter verifies your documentation, calculates your DTI, and checks your credit. If everything looks clean, they approve you.

Step 6: Receive your pre-approval letter. This document states your approved loan amount, loan type, and any conditions you must satisfy.

Documents You’ll Need to Gather

Gathering these documents ahead of time speeds up the process considerably:

  • Two most recent pay stubs covering 30 days
  • W-2 forms from the past two years
  • Two years of federal tax returns (especially if self-employed)
  • Two to three months of all bank statements
  • Statements for retirement accounts, brokerage accounts, or other assets
  • Current mortgage or rental payment history
  • Driver’s license or other government ID
  • Divorce decree or child support documents if relevant

How Long It Takes and What It Costs

Most lenders turn around a pre-approval within a few business days. A credit union might take slightly longer due to membership requirements. Online lenders can sometimes do it in a single day.

Pre-approval itself is usually free. You might see an application fee or appraisal fee charged upfront, but itself pre-approval rarely carries costs. Some lenders do charge a small fee and then credit it back at closing.

Ask about this before you apply.

What Your Pre-Approval Letter Tells You (And What It Doesn’t)

Your pre-approval letter includes specific details that shape your home search. It states your approved loan amount, the loan program, and the interest rate you’re being quoted. You’ll also see the estimated monthly payment broken down by principal, interest, taxes, and insurance.

Here’s what the letter does not tell you. It doesn’t guarantee the final loan. It doesn’t verify the property itself.

The lender hasn’t appraised any home yet. The terms can change if your financial situation shifts. And crucially, the pre-approval amount is the maximum you qualify for, not the price you should pay.

Understanding Your Loan Amount and Interest Rate

The approved amount on your letter is the ceiling. A lender might approve you for $450,000, but your monthly payment at that level could represent 40% of your take-home pay. Just because the bank says you can borrow it doesn’t mean you should.

Your interest rate gets quoted based on your credit score, down payment size, loan type, and current market conditions. A higher credit score secures a lower rate. A larger down payment reduces your loan-to-value ratio, which also improves your rate.

Why Your Credit Score and DTI Are the Two Big Numbers

Your credit score determines your rate tier. FHA loans allow scores as low as 580 with a 3.5% down payment. Conventional loans typically require at least 620.

VA loans have no official minimum but most lenders want 620 or above.

Your DTI caps how much house you can afford. Gross income of $6,000 per month with $2,500 in existing debts gives you a DTI of 41.7%, near the conventional ceiling. You could only qualify for a minimal additional monthly payment, which translates into a surprisingly small approved amount.

Common Mistakes That Ruin a Pre-Approval

Borrowers sabotage their pre-approvals more often than you’d think. The process runs smoother when you understand the common pitfalls.

Changing jobs during the process. Lenders verify employment twice, once at pre-approval and again before closing. A job change, especially to a different industry or a commission-based role, can reset your underwriting entirely.

Financing a new car. New monthly debt changes your DTI. A $500 car payment might push you over the lender’s threshold, killing your approval.

Maxing out credit cards. High balances raise your credit utilization and drop your score. Even if you plan to pay them off later, the lender sees the risk now.

Depositing undisclosed cash. Large deposits from friends or savings accounts you can’t document raise red flags. Underwriters need to confirm funds came from legitimate sources.

Ignoring the credit pull. Multiple hard inquiries within a short window can lower your score. Rate shopping is fine within a 30-45 day period, as scoring models treat it as one inquiry, but spreading applications across months hurts you.

Financial Moves to Avoid After You’re Pre-Approved

Rule of thumb: keep your finances exactly as they were when you got approved. Pay your bills on time. Don’t open new credit accounts.

Don’t close old ones either, since that shortens your credit history.

Your down payment funds need to stay put. Moving money between accounts is fine, but document the trail. Underwriters flag large deposits that don’t match your income, and unexplained funds require extra paperwork or can cause denial.

Timing Traps and Expired Letters

Pre-approval letters expire, typically after 60 to 90 days. If you haven’t found a home within that window, renew your approval. The lender will re-pull your credit and re-verify your income, which costs you a few points on your score but keeps your offer credible.

Shopping period matters too. Your credit score gets dinged by each hard inquiry. Multiple lenders pulling your credit within a 45-day window count as one inquiry for scoring purposes, so don’t drag your rate shopping across months.

How to Choose the Right Lender for Your Pre-Approval

Homebuyer reviewing mortgage preapproval letter on laptop at home.


Your choice of lender shapes your entire home-buying experience. Interest rates matter, but so do communication, speed, and willingness to work with your specific financial situation.

Bank vs. Credit Union vs. Mortgage Broker: Where to Start

National banks offer convenience and competitive rates for existing customers. If you have a long relationship with your current bank, they might offer relationship discounts.

Credit unions often provide lower fees and more flexible underwriting. Their loan officers typically have more time to walk first-time buyers through the process. Membership requirements exist, but most credit unions accept anyone who lives in their service area.

Mortgage brokers shop your file across multiple lenders. They see wholesale rates and can match you with a lender suited to your financial profile. This works well for self-employed borrowers or those with non-traditional income.

The table below summarizes the key differences:

Factor National Bank Credit Union Mortgage Broker
Rate comparison Limited to their products Limited to their products Multiple lenders
Service level Varies, sometimes impersonal Often highly personal High touch
Turnaround time 3-7 days 2-5 days 3-7 days
Fees Low to moderate Usually lowest Moderate, sometimes paid by lender
Best for Existing customers First-time buyers Complex income situations

Questions to Ask Before Submitting Your Application

You’re about to share your most sensitive financial data. Ask these questions first:

  • What is your typical pre-approval turnaround time?
  • Do you offer a rate lock at pre-approval, or only after I have a contract?
  • What fees do you charge that I won’t see on the Loan Estimate?
  • Will you service my loan or sell it to another company?
  • What credit score do I need for your best rate?
  • Have you underwritten self-employed borrowers or buyers with non-traditional income?

Asking these questions helps you avoid surprises later. A lender who hesitates or gives vague answers on rate lock policy may cost you thousands if rates rise while you shop.

Frequently Asked Questions

How long does a mortgage pre-approval last?

Most pre-approval letters remain valid for 60 to 90 days. After that window, lenders re-verify your credit, income, and assets before renewing. If you haven’t found a home by then, simply ask your lender to refresh the letter.

Expect another hard credit inquiry.

Does getting pre-approved hurt my credit score?

A pre-approval requires a hard credit inquiry, which typically lowers your score by 2 to 5 points. That impact fades within a few months. Multiple inquiries within a 45-day period count as a single inquiry for scoring purposes, so rate shopping won’t compound the damage.

How much does a pre-approval cost?

Most lenders charge nothing for a pre-approval. Some may request an application fee or appraisal fee upfront, but that’s rare for this stage. Always ask before submitting your application.

If a lender demands significant fees just for pre-approval, that’s a red flag.

What’s the difference between pre-approval and pre-qualification?

Pre-qualification is an informal estimate based on numbers you provide. No documents, no credit check, no verification. Pre-approval requires full documentation, a hard credit pull, and actual underwriting review.

Sellers and agents only take pre-approvals seriously.

Can I be denied after getting pre-approved?

Yes. Your pre-approval is conditional on keeping your financial situation stable. If you change jobs, take on new debt, or fail to document large deposits, the lender can revoke approval.

The property itself also needs to appraise at the purchase price for final approval.

Should I get pre-approved before looking at houses?

Absolutely. Pre-approval tells you your real budget, strengthens your offers, and speeds up closing. Looking at homes without one wastes time on properties outside your range.

In competitive markets, sellers often refuse to consider offers without a pre-approval letter attached.

Your Next Steps: From Pre-Approval to Closing Day

You’ve got the letter in hand. Now the real work begins. Your pre-approval sets the ceiling, but your actual home search needs a personal budget below that number.

Factor in property taxes, homeowners insurance, HOA dues, and maintenance costs when calculating your comfortable monthly payment.

When you find a home and your offer gets accepted, the lender orders an appraisal. That’s the third-party valuation confirming the home is worth what you agreed to pay. If it appraises low, you’ll need to renegotiate price, bring more cash, or walk away.

Between contract signing and closing, keep your finances exactly as they were during pre-approval. That means no new credit cards, no car loans, no undisclosed deposits. Underwriters re-check everything right before closing, and borrowers lose loans at the finish line more often than you’d expect.

Closing day typically happens 30 to 45 days after your offer is accepted. You’ll review the Closing Disclosure, wire your down payment and closing costs, and sign a mountain of paperwork. After that, the keys are yours.

Getting pre-approved early made the entire journey smoother.

How to Write an Honest Product Review That Helps

You’ve probably read a review that felt off. The language was glowing, every flaw got explained away, and by the end you still had no idea if the product was worth your money. That’s the exact problem honest reviews solve.

Learning how to write an honest product review isn’t just about listing features. It’s about building trust with readers who are deciding whether to spend their hard-earned cash based on your words.

The stakes are higher than most reviewers realize. According to the Federal Trade Commission (FTC), failing to disclose affiliate relationships or sponsored products can land you in legal trouble. Beyond compliance, your credibility is on the line.

A single dishonest review can destroy years of reader trust, and rebuilding that trust is nearly impossible. The good news? Writing honestly is a skill you can learn, and this guide walks you through every step.

Why Honest Reviews Matter More Than Ever

Consumers are drowning in options. Every product category has dozens of similar items, and most claims sound identical. That’s why people hunt for reviews in the first place.

They want someone to cut through the marketing noise and tell them the truth, even when it’s uncomfortable.

The problem is that fake reviews are everywhere. Aggregate research suggests that anywhere from 15% to 30% of online reviews are fabricated or incentivized. That means readers have learned to be skeptical of everything they read.

Your honest review stands out precisely because it’s honest, but only if readers can tell the difference.

Here’s what makes honest reviews valuable:

  • They save readers money by preventing bad purchases.
  • They save readers time by narrowing down real options.
  • They build long-term trust that keeps readers coming back.
  • They establish you as a credible voice in your niche.

Readers aren’t looking for perfection. They’re looking for predictability. A review that says “this product failed after three weeks of daily use” is more helpful than one that says “this product is amazing” with zero context.

Honesty, even when it’s negative, is what keeps readers loyal.

The other side of this coin is your own reputation. When you recommend a product that turns out to be terrible, readers remember. They may not unsubscribe immediately, but they’ll hesitate before trusting your next recommendation.

One honest negative review builds more credibility than ten glowing ones.

What an Honest Review Actually Looks Like

An honest review isn’t just a list of pros and cons. It’s a complete picture that gives readers the information they need to make an informed decision. That includes both what you liked and what you didn’t, with context for both.

Here are the core components of a genuinely honest review:

  • Real testing experience: You actually used the product, not just read the specs.
  • Clear context: You explain who the product is for and who it isn’t for.
  • Specific details: You name exact features, measurements, and performance observations.
  • Balanced perspective: You include negatives alongside positives, not just a token “could be better.”
  • Full disclosure: You state whether you bought the product or received it free.
  • Clear verdict: You give a direct recommendation with reasoning.

A review that skips any of these feels incomplete. A review that skips most of them feels like an ad. The most honest reviews read like a conversation with a knowledgeable friend who wants you to make the right choice, even if that choice isn’t buying the product.

The tone matters too. Honest reviews don’t shout. They don’t use words like “amazing” or “life-changing” for a decent blender.

They describe what happened when they used the product, and they let readers draw their own conclusions.

One key distinction: honesty doesn’t mean being mean. You can write a critical review without being cruel. The goal is to be accurate and fair, not to punish a manufacturer.

That means acknowledging when a product works well for its intended use case, even if it’s not right for you.

The Real-World Testing Process

You can’t write an honest review without real experience. That means actually using the product, not just examining it or reading the manual. Real testing takes time and structure, and the results are worth it.

Here’s a practical testing process that produces honest, useful reviews:

  1. Document first impressions immediately: Write down your first reaction when opening the box. How does it feel in hand? Does it look like the photos? Is it heavier or lighter than expected? First impressions are valuable because they capture what readers will experience.

  2. Test the primary use case first: Use the product exactly as intended before trying anything creative. If it’s a backpack, pack it and wear it. If it’s a blender, blend something. If it’s a phone case, put your phone in it. The basics matter most.

  3. Test secondary use cases: Products often get used beyond their primary function. Does the backpack work for travel? Does the blender crush ice? Does the phone case survive a drop? These secondary tests reveal whether a product is versatile or single-purpose.

  4. Note the details: Track things like durability, ease of cleaning, button placement, and material quality. These small details often matter more than big specs because readers live with them daily.

  5. Take notes throughout: Don’t rely on memory. Keep a running log of observations, both positive and negative. This helps you write a specific review rather than a vague one.

  6. Revisit the product after a week: First impressions fade and issues emerge. A product may feel great on day one but show flaws by day seven. That’s exactly what readers need to know.

The timeline matters. Testing a product for one hour and calling it a review is dishonest in a different way. You’re not lying, but you’re not giving readers the information they need either.

Honest reviews require meaningful time with the product.

For consumable products like skincare or food, testing takes even longer. For durable goods like appliances, it can take weeks to spot issues. The key is to be transparent about how long you tested and what held up versus what didn’t.

How to Handle Bias, Free Products, and Brand Relationships

This is the hard part. Receiving free products feels great, and building relationships with brands is rewarding. But both create bias that can quietly compromise your honesty.

The first step is disclosure. The FTC requires you to clearly state when you received a product for free or were paid to review it. That’s not optional.

It’s also in your best interest because readers are more likely to trust a disclosed review than an undisclosed one they suspect of being paid.

Here’s how to manage bias practically:

  • Always disclose: Even if you paid for the product yourself, mentioning that you bought it adds credibility. If you received it free, say so clearly and prominently.
  • Don’t promise favorable coverage: Accept free products only on your terms. If a brand asks for a “positive review in exchange,” turn it down.
  • Keep your standards consistent: Review free products with the same criteria you use for products you buy. That means testing just as thoroughly.
  • Acknowledge the relationship: If you’ve worked with a brand before, mention it. Readers deserve to know if you have an ongoing relationship.
  • Avoid exclusivity deals: If a brand requires you to delete or never publish a negative review, that’s a red flag. Walk away.

Bias also comes from less obvious places. Confirmation bias makes you focus on what you expect to see. Anchoring makes your second impression follow your first.

Even your mood on testing day can affect your perception.

The best way to counter bias is to structure your testing. Follow the same process for every product, and you’ll catch exaggerations. If you usually test for a week, do that consistently.

If you usually take notes, keep doing it. Structure is the enemy of bias.

Brand relationships aren’t inherently bad. Many excellent reviewers work closely with brands while maintaining honesty. The key is transparency and a willingness to say no.

When readers know you’re honest, they trust your brand partnerships more, not less.

Mistakes That Ruin Credibility (and How to Avoid Them)

A male hand measuring smartphone dimensions using digital calipers.

Most reviewers don’t set out to be dishonest. They make predictable mistakes that erode trust over time. Here are the most common ones and how to avoid them.

Reviewing without testing: Writing a review based on specifications or manufacturer claims is not a review. It’s a summary. Readers can read specs themselves.

They come to you for real experience.

Using vague language: Words like “good” and “nice” don’t tell readers anything. Be specific. Say “the zipper is smooth and never snags” instead of “the backpack is good quality.”

Ignoring negatives: Every product has flaws. Ignoring them makes your review feel incomplete at best and dishonest at worst. Address negatives honestly, even if you don’t consider them dealbreakers.

Letting price influence quality: A $20 product can be excellent for its price, and a $200 product can be disappointing. Review each product against its price point and intended audience, not against products in a completely different category.

Overhyping minor features: If a product has a feature that exists but isn’t useful, say so. Don’t praise a “water-resistant” jacket that only handles light rain.

Failing to disclose: This is the fastest way to lose credibility. If readers discover you were paid or received free products without disclosure, they’ll question every review you’ve ever written.

Writing for brands instead of readers: When you start crafting reviews to please manufacturers, you’ve lost your way. Your audience is the reader who might buy the product, not the brand that sent it.

Not updating reviews: Products change over time. A review you wrote two years ago may no longer be accurate. Update your reviews when you have new information, and note when you’re providing long-term feedback.

The solution to all these mistakes is simple: treat every review as if the person reading it is about to spend their own money. Because they are.

How to Structure a Review People Trust

A well-structured review respects your reader’s time. It gives them the answer they need quickly, then provides the details that back it up. Most people skim reviews before reading them fully.

Your structure should accommodate both behaviors.

Here’s a proven framework:

  • Opening verdict: State your overall recommendation in the first paragraph. Readers want to know if you’d buy it again before they read your reasoning.
  • Context and testing: Explain who you are, how you tested the product, and for how long. This establishes your credibility.
  • Key specs and features: Cover the important details. Name the materials, measurements, and performance factors that matter.
  • The good: Start with what genuinely works. Be specific about why it works and who it benefits.
  • The bad: Address what doesn’t work. Explain the trade-offs clearly. If a flaw only affects certain users, say so.
  • Comparison context: Position the product against alternatives. Is it better or worse than similar options? For whom?
  • Final verdict: End with a clear recommendation and a brief recap of your reasoning.

This structure works because it mirrors how readers make decisions. They check the verdict, scan the context, then dive into details that matter to them. A reader looking for a laptop bag doesn’t need to know about the camera any more than your verdict states.

The order matters more than you’d think. When you bury the verdict at the end, readers skim the whole review looking for it. When you reveal it upfront, readers can focus on the reasoning.

That makes your review more useful, not less.

Frequently Asked Questions

How long should I test a product before writing a review?

The ideal testing period depends on the product category. For durable goods like appliances or tools, test for at least two to four weeks. For consumables like skincare or food, test multiple times across several days.

The key is meaningful usage, not a specific number of days. A week of daily use beats a full month of occasional use.

Do I need to disclose free products or affiliate links?

Yes, absolutely. The Federal Trade Commission requires disclosure when you receive free products or earn commissions from affiliate links. Place your disclosure clearly and prominently, not buried in a footer.

Readers trust reviewers who are transparent about their relationships.

Should I include negative reviews about products I received for free?

Yes. Accepting a free product doesn’t obligate you to write a positive review. If the product has serious flaws, your readers deserve to know.

Most brands expect honest feedback. If a brand pressures you for a positive review, that’s a significant red flag.

What if I don’t have time to test a product thoroughly?

Then either decline the review or state your limited testing time upfront. A review based on a single use is not an honest review. Readers assume you’ve put meaningful time into the product.

If you haven’t, say exactly how long you used it and let readers decide how much weight to give your opinion.

Can I write an honest review if I have a relationship with the brand?

Yes, as long as you disclose the relationship and maintain your standards. Review the product with the same criteria you’d use for any other. If the relationship affects your objectivity, acknowledge that too.

Readers can handle nuance when you’re honest about it.

Putting It All Together: Your Review-Writing Checklist

Before you hit publish, run through this checklist to make sure your review is honest, useful, and trustworthy.

  • How many days, weeks, or uses does your review cover?
  • Why: Do you clearly state who the product is for and who it isn’t for?
  • Disclosure: Did you mention how you obtained the product and any affiliate relationships?
  • Specifics: Did you name actual features, measurements, and observations instead of vague praise?
  • Balance: Did you include at least one genuine negative, even if minor?
  • Comparison: Did you position the product against alternatives readers might consider?
  • Verdict: Did you give a clear recommendation with reasoning?

A review that passes this checklist will feel honest because it is honest. It will also stand out in a sea of generic content built around fake experience and vague claims.

Remember the goal. You’re writing to help someone decide whether to spend their money. That’s a responsibility worth taking seriously.

When you treat it that way, your readers will notice, and they’ll keep coming back for your recommendations.

One final thought on the bigger picture. The internet is full of noise. Fake reviews, paid placements, and exaggerated claims make it harder for readers to trust anything they read.

Your honest review is a counterweight to that noise.

Every time you publish a transparent, well-tested review, you’re building something valuable. You’re building a reputation that compounds over time. Readers who trust you today will share your work tomorrow.

Brands will respect your honesty, even when it’s critical.

Start small. Write one honest review this week. Use the checklist.

Disclose everything. Be specific about what worked and what didn’t. You’ll notice the difference in how readers respond.

That’s the real secret to writing honest reviews. It’s not a technique you master once. It’s a habit you practice every time you sit down to write.

The more you do it, the more natural it becomes. And the more your readers will thank you for it.

Each review you publish reinforces your standing as a reliable voice in your niche. That standing opens doors. Brands will send you products because they value your honest feedback.

Readers will trust your recommendations because you’ve proven you won’t sugarcoat flaws. Your archive of reviews becomes a portfolio that speaks for itself.

So approach your next review with confidence. You now have the framework, the testing process, and the disclosure practices to do it right. The only thing left is to sit down and write.

Your readers are waiting, and they’re counting on you to tell them the truth.

There’s no perfect review, and that’s okay. Every review you publish will have blind spots, and every reviewer makes mistakes. What matters is that you keep learning and keep refining your approach.

Pay attention to how readers respond. When they leave comments asking for more detail, add that detail next time. When they thank you for warning them about a flaw, keep being honest about flaws.

That feedback loop makes you better with every piece you publish.

Your voice matters in this space. Readers are tired of feeling manipulated by marketing disguised as opinion. When they find a reviewer who tells it straight, they stick around.

They tell their friends. They trust your words.

So go write that review. Test the product properly. Disclose your relationships.

Share both the wins and the failures. And remember why you started: to help someone make a smarter decision with their own money. That’s honest review writing, and it never goes out of style.

Your readers aren’t looking for perfection. They’re looking for predictability and reliability. They want to know that when you say something works, it works.

When you say something falls short, you can show them exactly where and why.

The best time to build that reputation was your first review. The second best time is right now. Every piece you publish from this point forward adds to the foundation you’re building.

Even a short review of a simple product counts. Even a critical take that earns you pushback builds credibility.

So don’t overthink it. Don’t wait for the perfect product or the perfect moment. Pick something you’ve actually used, be honest about your experience, and share it.

The rest takes care of itself.

Two-Factor Authentication Explained: What and Why

You type your password, hit enter, and you’re in. That single step has protected your accounts for decades, but it’s just not enough anymore. So what is two factor authentication, and why does every major platform keep pushing you to turn it on?

The short answer: it’s a second check that proves you’re really you, even if someone steals your password.

Think of it like locking your front door versus having a deadbolt. A password is the regular lock. Two-factor authentication adds the deadbolt, and it only opens with something you physically have.

As of 2026, over 80% of data breaches involve compromised passwords, which is why security standards like those from NIST now recommend 2FA as a baseline. Let’s walk through exactly how it works, which type you should use, and how to set it up without getting locked out of your own accounts.

Quick Answer

Two-factor authentication (2FA) adds a second verification step after your password. You prove who you are with something you know, plus something you have or are. That’s usually a code from an app, a text message, or your fingerprint.

Even if a hacker steals your password, they still can’t get in. It’s the single most effective way to protect your online accounts.

Key Takeaways: The Four Things You Must Remember About 2FA

  • Passwords alone are fragile. They get stolen in data breaches, reused across sites, and phished from unsuspecting users every single day.
  • Not all 2FA is equal. SMS codes are better than nothing, but authenticator apps are more secure, and hardware keys are the gold standard.
  • Backup codes are your lifeline. If you lose your phone and didn’t save them, you can lose access to your accounts permanently.
  • Set it up on your email first. Your email is the master key to everything else, so it deserves your strongest protection.

How Two-Factor Authentication Works (The Three Authentication Factors)

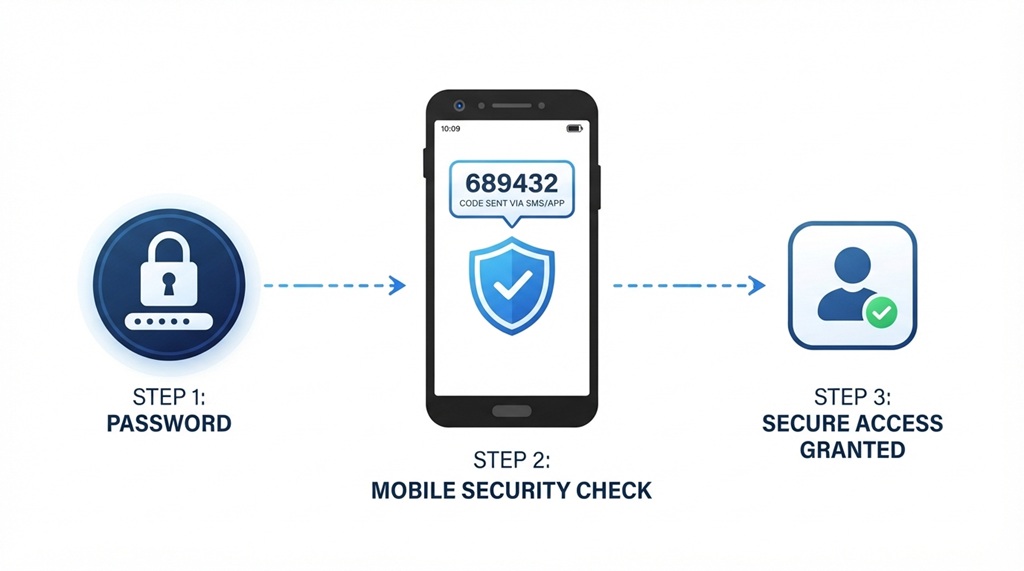
Two-factor authentication works by requiring two different types of proof before letting you into an account. Each piece of proof falls into one of three categories: something you know, something you have, or something you are. A password is something you know.

Your phone or a security key is something you have. Your fingerprint or face is something you are.

Most 2FA setups combine a password plus one of the other two factors. The key word here is “different.” If you use two passwords, that’s still just one factor. The whole point is that each layer comes from a separate category, so an attacker can’t easily steal both.

The Three Types of Proof: Knowledge, Possession, and Inherence

  • Knowledge factors are things you know, like passwords, PINs, or security questions. Unfortunately, these are also the easiest for hackers to guess or steal.
  • Possession factors are physical things you have, like a smartphone, a hardware key, or a smart card. An attacker would need to physically steal the device.
  • Inherence factors are biological traits, like fingerprints, facial recognition, or voice patterns. These are hard to copy but not impossible to spoof.

Why a Password Alone Is No Longer Enough

Passwords have a fundamental flaw: they live on the internet. When you use a password on a website, that site stores it somewhere. Hackers target those databases constantly, and when they succeed, they publish the password lists online.

Since many people reuse passwords across sites, one breach can unlock dozens of accounts.

Even a unique, complex password isn’t safe from phishing. A fake login page that looks identical to your bank’s site can trick you into typing your credentials without realizing anything’s wrong. 2FA stops that attack cold, because the hacker gets your password but still lacks the second factor.

The Four Main Types of 2FA: Which One Should You Use?

There are four main ways to receive that second verification, and they’re not all created equal. Your choice depends on the account you’re protecting, your tolerance for inconvenience, and how valuable your data is to a hacker. Here’s the honest breakdown of each.

SMS Text Codes: Convenient but Vulnerable

SMS 2FA sends a one-time code to your phone via text message. It’s the most widely recognized method because it’s been around the longest and requires no extra apps. You type the code in after your password, and you’re done.

For someone setting up 2FA for the first time, it feels easy and familiar.

The problem is the delivery method. Text messages travel through your mobile carrier’s network, and hackers have found ways to intercept them. A technique called SIM swapping involves tricking your carrier into transferring your phone number to a new SIM card in the hacker’s possession.

Once that happens, all your texts, including your 2FA codes, go straight to them. The National Institute of Standards and Technology (NIST) has even discouraged SMS as a primary 2FA method for this reason.

Use SMS if: you have no other option, or you’re setting up 2FA for a relative who isn’t tech-savvy. It’s better than no protection at all, but it’s the weakest link in the 2FA chain.

Authenticator Apps: The Best Balance of Security and Convenience

Authenticator apps like Google Authenticator, Microsoft Authenticator, and Authy generate six-digit codes directly on your phone. The codes refresh every 30 seconds, and they’re created locally on your device rather than being sent over a network. That’s a crucial difference, because there’s no text message to intercept and no carrier involved.

Setup involves scanning a QR code on your computer screen with the app on your phone. From then on, the app produces codes that sync with the website’s server. Since the code never travels through a network, SIM swapping won’t help an attacker.

They’d need physical access to your phone, which is a much higher bar.

Use an authenticator app if: you want the best combination of security and ease for your personal email, banking, and social media. This is the default recommendation for most people.

Hardware Security Keys: The Gold Standard for High-Value Accounts

Hardware security keys are small USB or NFC devices that you plug in or tap to complete a login. They don’t display codes. Instead, they physically perform a cryptographic handshake with the website, proving you possess the key.

Brands like YubiKey and Google’s Titan Key are the most common examples.

These keys are nearly immune to phishing. Even if you type your password into a fake website, the key won’t authorize the login because it verifies the site’s identity first. That makes them ideal for protecting cryptocurrency wallets, work accounts, or anyone facing credible threats like journalists or executives.

Use a hardware security key if: you handle cryptocurrency, work in a sensitive field, or feel your accounts might be targeted specifically. They cost between $20 and $70, and they’re worth every penny for high-value accounts.


Digital diagram showing password and phone verification layers for two-factor authentication.

Push Notifications: Easy but Prone to “Push Fatigue”

Push authentication sends a notification to your phone asking you to approve or deny a login attempt. You tap “Yes” if it’s you, and “No” if it isn’t. It’s arguably the fastest and easiest method, since there’s no code to type at all.

The catch is a phenomenon called push fatigue. If a hacker has your password, they can trigger dozens of login attempts in rapid succession. Your phone buzzes repeatedly until you tap “Yes” just to make it stop, granting them access.

Some platforms have added a safeguard, like requiring you to match a number displayed on the login screen. If your app doesn’t do that, consider switching methods.

Use push notifications if: you want maximum convenience and you’re on a platform that requires a confirmation number. Otherwise, an authenticator app is a safer bet.

Side-by-Side Comparison of 2FA Methods

Method Security Level Convenience Phishing Resistant Best For
SMS Text Code Low High No First-time users, no alternatives
Authenticator App High Medium Partially Most personal accounts
Hardware Key Very High Low Yes Crypto, work, high-risk users
Push Notification Medium Very High Partially Quick logins, low-risk apps

How to Set Up 2FA on Your Most Important Accounts (Step-by-Step)

Setting up 2FA takes about five minutes per account. You don’t need to do every account in one sitting. Start with the ones that matter most, then work your way down the list.

The process is similar across platforms, and once you’ve done one, the rest feel familiar.

Step 1: Start With Your Primary Email

Your email is the master key to your digital life. Password resets for your bank, social media, and shopping accounts all route through your inbox. If a hacker gains control of your email, they can reset every other password you own.

Open your email provider’s security settings and look for “Two-Step Verification” or “Two-Factor Authentication.” Google, Microsoft, and Apple all offer this under their account settings. Follow the prompts to set up an authenticator app. Most providers also offer backup codes during setup, which you’ll want to save immediately.

Step 2: Protect Your Financial and Social Accounts

Once your email is locked down, move to your bank, PayPal, and cryptocurrency exchange. Financial accounts are the most direct target for thieves. Social media accounts matter too, since a hijacked account can be used to scam your friends and family.

Most banking apps support 2FA through push notifications or SMS codes. Use the best method available on each platform. For crypto exchanges, a hardware key is strongly recommended if you hold meaningful amounts.

Step 3: Save Your Recovery Codes Immediately

Here’s where most people trip up. When you enable 2FA, the platform gives you a set of one-time backup codes. These are meant for emergencies, like when you lose your phone.

Store them somewhere safe. Print them and put them in a drawer, or save them in a password manager.

If you lose your phone and didn’t keep the codes, recovery becomes a nightmare. You’ll spend hours proving your identity through automated systems, submitting forms, and waiting for customer service. Don’t let that be you.

Save the codes before you close the setup window.

Step 4: Prepare for a Lost or Stolen Phone

Even with backup codes, losing your phone is stressful. Take a minute to plan ahead. Authenticator apps like Authy offer encrypted cloud backup, which lets you restore your codes on a new device.

Google Authenticator now offers a transfer feature between phones. Microsoft Authenticator has similar options.

Set up your new phone before you wipe the old one, if possible. Most apps require you to scan a QR code or enter a setup key to transfer the account. Doing this while both phones work is far easier than recovering after a loss.

Common 2FA Mistakes That Weaken Your Security

Even with 2FA enabled, people still get hacked. The problem isn’t usually the technology. It’s how people use it.

Here are the four most common mistakes we see in our research, and how to avoid them.

Mistake 1: Using SMS Codes When an Authenticator App Is Available

SMS codes are the easiest target for attackers. SIM swapping attacks have been on the rise for years, and carriers haven’t fully solved the problem. If your bank or email provider offers an authenticator app, use it.

The extra minute of setup time is worth the protection.

Mistake 2: Ignoring the Backup Codes

Most people skip saving backup codes because they think they’ll never need them. Then they lose their phone, and they’re locked out of everything. Print the codes.

Put them somewhere safe. Your future self will thank you.

Mistake 3: Confusing 2FA With Immunity From Phishing

2FA doesn’t make you invincible. If you approve a push notification without reading it, or type a code into a fake website, you’re still vulnerable. Always verify the login request is really from you before approving.

Mistake 4: Setting Up 2FA on Every Account Except the Ones That Matter

It’s easy to enable 2FA on your social media accounts and forget about your email. But your email is the master key to everything. Prioritize email, banking, and crypto first.

The rest can wait.

2FA vs. MFA vs. Password Managers: Where Does Each Fit?

These three terms get thrown around a lot, and people often confuse them. They’re related but distinct tools that work together. Here’s the breakdown.

Two-factor authentication specifically requires two different types of proof. Multi-factor authentication (MFA) is the broader umbrella term. It requires two or more factors, which is technically the same thing, but MFA can also include additional layers like risk checks. In practice, most people use the terms interchangeably.

Password managers are a separate tool entirely. They generate and store strong, unique passwords for every site you use. What makes them relevant to 2FA is that many password managers now support one-time codes alongside your passwords.

That means you can use your password manager as your authenticator app, keeping everything in one place.

Here’s how they stack up:

Tool What It Does How It Relates to 2FA
Password Manager Stores credentials Can generate and store 2FA codes
2FA App Generates time-based codes The second factor itself
MFA System Combines multiple checks The overarching security framework
Hardware Key Physical cryptographic proof The strongest second factor available

Frequently Asked Questions About Two-Factor Authentication

Is two-factor authentication the same as two-step verification?

They’re similar, but not identical. Two-step verification usually means a password plus a code sent via SMS or email, which is technically one factor delivered two different ways. True 2FA requires two different types of proof, like a password and a fingerprint.

In practice, many platforms use the terms loosely, so check the settings to see what’s actually being used.

What happens if I lose my phone with my authenticator app on it?

If you saved your backup codes, you can use one to log in from a new device. If not, you’ll need to go through the platform’s account recovery process, which typically involves verifying your identity through alternative means. That’s why saving backup codes during setup is so critical.

Can 2FA be hacked?

Yes, but it’s much harder than bypassing a password alone. The most common attacks involve SIM swapping for SMS codes and phishing for push notifications. Authenticator apps and hardware keys are significantly more resistant to these attacks.

Does 2FA work on all websites?

Most major platforms support it, including Google, Microsoft, Apple, Facebook, and most banks. Smaller or older websites may not offer it. For sites that don’t, using a unique, complex password through a password manager is your best alternative.

How long does it take to set up 2FA?

Most accounts take about two to five minutes to configure. Scanning a QR code, entering a verification code, and saving backup codes is the full process. Doing it for your email, bank, and social media accounts takes roughly 15 minutes total.

Is 2FA worth it if I have a strong password?

Yes, absolutely. A strong password protects you against guessing and brute-force attacks, but it does nothing against data breaches or phishing. 2FA adds a second layer that stops those attacks cold, even if your password is compromised.

Final Recommendation: Your 10-Minute Setup Plan for Better Account Security

Two-factor authentication is the closest thing to a guaranteed win in cybersecurity. It’s free, quick to set up, and dramatically reduces your risk of being hacked. The only real cost is a few extra seconds each time you log in.

Start with your email account, since it’s the gateway to everything else. Use an authenticator app rather than SMS if your provider supports it. Save the backup codes immediately.

Then move on to your banking, crypto, and social media accounts.

If you handle cryptocurrency or work with sensitive data, invest in a hardware key. It’s the single best purchase you can make for your digital security. For everyone else, a free authenticator app is more than sufficient.

Install the app now, set up your first account, and save those backup codes. Ten minutes today saves you from a potential disaster tomorrow.

How to Set Up 2FA on the Most Common Platforms

The exact steps vary by platform, but the pattern is consistent across all of them. Here’s a quick reference for the biggest ones:

Google (Gmail): Go to your Google Account settings, select Security, then find “2-Step Verification.” You’ll be prompted to sign in again, then you can choose your preferred method. Google strongly recommends its own Authenticator app or hardware keys.

Apple (iCloud): Apple calls it “Two-Factor Authentication” and it’s built into your Apple ID settings. You’ll see a prompt on your trusted devices when you sign in. Apple doesn’t offer an authenticator app in the traditional sense; instead, it relies on device-based approval and will text a code to your number if you have no other devices available.

Microsoft (Outlook, Windows): Under your Microsoft account security settings, you’ll find “Security info” and the option to add a sign-in method. You can register an authenticator app, a phone number for codes, or a hardware key. Microsoft Authenticator is particularly smooth here because it supports passwordless sign-in and multi-device sync.

Banking apps: Most major financial institutions support either SMS or a push notification through their own mobile app. Some are moving toward authenticator apps, but adoption is slower in the banking sector.

If you can’t find the setting, search the platform’s help center for “2FA,” “two-step verification,” or “security key.”

Exercise: The Natural Antidepressant

You know that foggy, heavy feeling when your brain just won’t cooperate? The one where getting off the couch feels like climbing a mountain, and your thoughts keep circling back to the same worries? Exercise is one of the most effective ways to cut through that mental fog.

The benefits of regular exercise for mental health go far beyond the typical “feel-good endorphins” line you’ve heard a hundred times.

We’re not talking about becoming a marathon runner or spending hours in a gym. The research supporting exercise as a mental health tool is substantial. For instance, the World Health Organization recommends at least 150 minutes of moderate physical activity per week for adults, and studies consistently show that even this modest amount can significantly reduce symptoms of depression and anxiety.

The best part? You don’t need to wait months to feel the effects. Let’s break down what actually happens in your brain when you move your body, and how you can use this knowledge to feel better starting today.

Quick Answer

Regular exercise directly improves mental health by reducing depression and anxiety symptoms, improving sleep, and boosting overall mood. It works by releasing neurotransmitters like serotonin and endorphins, reducing stress hormones like cortisol, and promoting brain health through BDNF production. You don’t need intense workouts.

Even brisk walking for 30 minutes, five days a week, can produce meaningful improvements in eight to ten weeks.

Key Takeaways

  • Exercise works as a natural antidepressant. Studies show it can be as effective as medication for mild to moderate depression, without the side effects.
  • Consistency beats intensity. A 30-minute moderate walk you actually do is better than an intense workout you skip.
  • Acute effects are real. A single session can reduce anxiety for several hours, making exercise a useful in-the-moment coping tool.
  • Timeline matters. Noticeable mood improvements typically appear after 8-10 weeks of consistent activity, not after one workout.
  • Exercise is not a replacement for clinical care. If you’re experiencing severe symptoms, professional help is essential, and exercise works best alongside treatment.

Why Exercise Isn’t Just About Your Body

We’ve all heard the phrase “healthy body, healthy mind.” But it’s not just a saying. The connection between your physical activity and your mental state is deeply biological. When you exercise, you’re not just working your muscles.

You’re directly influencing the chemistry and structure of your brain.

Here’s the thing: your brain doesn’t really distinguish between running from a tiger and running on a treadmill. Both trigger a cascade of physiological responses designed to help you survive. Your heart rate increases, blood flow to the brain rises, and stress hormones like cortisol and adrenaline are released.

In a truly dangerous situation, this is your fight-or-flight response. But when you’re exercising, you’re deliberately triggering this response in a safe, controlled environment.

This is where the magic happens. Your brain learns to handle stress. Regular exercise can actually make your stress response system, known as the hypothalamic-pituitary-adrenal (HPA) axis, more resilient.

That means everyday stressors like a demanding boss or a tight deadline trigger a smaller, less overwhelming response. You become better equipped to handle life’s curveballs without spiraling into anxiety or a bad mood.

Physical activity also forces you to pay attention to your body, pulling your focus away from the constant stream of thoughts in your head. This is similar to mindfulness, giving you a break from rumination and worry. It’s a practical, accessible way to hit the reset button on a stressed-out mind.

What Exercise Actually Does to Your Brain

When we talk about the mental health benefits of exercise, we’re talking about real, measurable changes in your brain. It’s not just psychological. It’s biochemistry.

Let’s look at the key players.

The Big Three: Serotonin, Dopamine, and Endorphins

Exercise directly influences your brain’s neurotransmitter levels, the chemical messengers that regulate mood, motivation, and pleasure.

  • Serotonin is often called the “feel-good” neurotransmitter. Low levels are linked to depression. Exercise increases its production and release, which helps stabilize your mood and improve your sense of well-being.
  • Dopamine is the reward and motivation chemical. It’s responsible for that sense of accomplishment. Exercise boosts dopamine, which can improve focus and combat the lack of motivation that often comes with depression.
  • Endorphins are your body’s natural painkillers. They bind to opioid receptors in the brain, reducing discomfort and producing a feeling of euphoria. This is the source of the “runner’s high,” but you don’t need to run a marathon to get it. A brisk walk can trigger a mild, pleasant release.

Beyond the Chemical High: BDNF and Brain Health

The most exciting research in recent years focuses on a protein called Brain-Derived Neurotrophic Factor, or BDNF. Think of it as fertilizer for your brain. It promotes the growth of new neurons and strengthens the connections between them, a process called neuroplasticity.

Higher levels of BDNF are associated with improved memory, learning, and cognitive flexibility. They’re also linked to a more resilient mood. Chronic stress and depression suppress BDNF production.

Exercise, particularly aerobic exercise, directly counteracts this, effectively helping your brain grow and adapt. It’s a powerful biological argument for exercise as a foundational pillar of mental health, not just a wellness trend. The image below illustrates the connection between neurons that BDNF helps strengthen.


A man smiling while stretching outdoors after completing a workout.

Turning Down the Stress Response

Exercise also helps regulate the HPA axis, which controls your body’s reaction to stress. Regular physical activity trains this system to be less reactive. It produces lower baseline levels of cortisol and reduces the peak response to stressful events.

This means you feel calmer and more in control when things get chaotic, rather than immediately jumping to panic or irritation.

The Real Impact on Depression and Anxiety

So, what does this biochemistry actually mean for you when you’re struggling with depression or anxiety? It means exercise is a potent, evidence-backed tool. It’s not casual advice from a fitness magazine.

It’s supported by clinical trials and major health organizations.

Exercise as an Antidepressant

Research has consistently found that exercise can significantly reduce depressive symptoms. Some studies have shown it to be as effective as selective serotonin reuptake inhibitors (SSRIs) for mild to moderate depression, without the side effects like weight gain or sexual dysfunction. It’s not an exaggeration to call exercise a natural antidepressant.

If you’re experiencing moderate depression, adding regular exercise to your routine could dramatically improve your symptoms. It works through multiple pathways, from boosting mood-regulating neurotransmitters to improving sleep and self-esteem, which creates a positive feedback loop for your mental state.

The Immediate Anxiety Buster

Anxiety responds differently to exercise than depression does. While the chronic benefits are real, exercise has an immediate, powerful effect on acute anxiety. A single session of moderate to vigorous activity can significantly reduce symptoms of anxiety for several hours afterward.

Why? Exercise activates the same physiological pathways as anxiety, such as increased heart rate and rapid breathing. By intentionally engaging in these activities, you effectively train your brain that these sensations are not dangerous.

It’s a form of exposure therapy. Over time, this can break the cycle of panic, where physical sensations trigger fear and worsen symptoms.

Who Benefits Most?

This isn’t a case of “one-size-fits-all.” Exercise is particularly effective for:

  • People with mild to moderate depression, where it can be a first-line intervention.
  • Individuals with generalized anxiety disorder, as a complement to therapy or medication.
  • People experiencing high levels of occupational stress.
  • Those with subclinical mood issues, simply feeling down or overwhelmed without a formal diagnosis.

However, if you’re dealing with severe depression, significant trauma, or bipolar disorder, exercise should not be your only treatment. It’s a powerful tool, but it’s not a substitute for professional mental health care.

How Much Exercise Do You Need for Mental Health Benefits?

This is the most practical question, and the answer is reassuring: you don’t need to be an athlete. You need to be consistent.

The Definitive Dose

The U.S. Department of Health and Human Services Physical Activity Guidelines for Americans recommend:

  • 150 to 300 minutes of moderate-intensity aerobic activity per week, or
  • 75 to 150 minutes of vigorous-intensity aerobic activity per week.

That breaks down to about 30 minutes a day, five times a week, of activities like brisk walking, swimming, or cycling. You can even break this into smaller chunks. Three 10-minute walks are just as effective as one 30-minute walk.

What Does “Moderate” Feel Like?

A good rule of thumb is the “talk test.” If you can talk while exercising, but you can’t sing a song, that’s moderate intensity. If you can only get out a few words between breaths, that’s vigorous.

The type of exercise matters less than whether you enjoy it and will stick with it. The best exercise for your mental health is the one you’ll actually do. This could be:

  • Brisk walking
  • Jogging or running
  • Swimming
  • Dancing
  • Strength training
  • Yoga or Pilates
  • Cycling
  • Team sports

How Soon Will I Feel Better?

Some effects are immediate. A single walk can reduce anxiety for hours. But for long-term mood improvement, you need patience.

That can feel frustrating, but it’s important to know that you’re not doing it wrong if you don’t feel like a new person immediately. Meaningful, lasting changes to your baseline mood typically take 8 to 10 weeks of consistent, regular exercise.

A Quick Comparison of Approaches

Approach Typical Frequency Time to Notice Mood Effect Best For
Moderate Aerobic 5x/week, 30 min 8–10 weeks Overall mood, depression
Vigorous Aerobic 3x/week, 25–50 min 4–6 weeks Stress relief, quick anxiety reduction
Strength Training 2–3x/week 8–12 weeks Self-esteem, depression
Yoga / Mind-Body 2–3x/week 6–8 weeks Anxiety, stress, mindfulness

Starting When You Feel Terrible: A Practical Guide

This is the hardest part, and I want to be honest about it. Depression saps your motivation. The very thing that could help you feel better feels impossible to start.

This is one of the most cruel symptoms of the condition.

The Motivation Paradox

Here’s the truth: you don’t need motivation to start, and you likely won’t feel motivated until after you’ve exercised. Motivation isn’t always the fuel; it’s often the reward. You have to act first, and the motivation follows.

So you need to stop waiting for a feeling that may never come.

Rule One: Engineer the Win

The key is to make the first step so small and easy that you can’t say no. Your goal isn’t to “exercise.” Your goal is to simply put on your shoes and walk outside. That’s it.

If that’s all you do, you win.

This approach, based on principles from behavioral activation therapy, works because it focuses on building positive feedback loops. You’ve accomplished something. That creates a small sense of mastery.

You start to feel slightly better, which makes it easier to do a bit more next time.

A Practical Step-by-Step for a Bad Day

  1. Define a “minimum viable” exercise. Promise yourself you’ll walk for just five minutes. That’s the entire goal. No more.
  2. Remove all barriers. Have your shoes, comfortable clothes, and water bottle ready the night before. If you think about it too much, you’ll talk yourself out of it.
  3. Start slow. Don’t worry about intensity or heart rate. Your only job is to get your body moving.
  4. Give yourself total permission to stop. If after five minutes you feel terrible, you can go home. It’s a win either way.
  5. Stack it with something you enjoy. Listen to a favorite podcast, call a friend, or just enjoy the weather. Associate exercise with pleasure, not obligation.

Often, the hardest part is that first step outside. Once you’re moving, the psychological resistance typically fades, and it’s easier to keep going. Remember, this is about building a sustainable habit, not achieving a perfect workout.

The 6 Mistakes That Sabotage Your Progress

Even when you know how helpful exercise is, it’s easy to fall into traps that undermine your efforts. It’s not about lacking willpower. It’s about common patterns that are simple to fix.

  • Mistake 1: Doing Too Much, Too Soon. The “go big or go home” mentality inevitably leads to burnout, injury, and disappointment. If you’re new to exercise, start with what feels easy and gradually build up. Adding just 10% more each week is a safe guideline.
  • Mistake 2: The All-or-Nothing Trap. If you miss one workout, you might think, “Well, I ruined the week, might as well quit.” One missed day is just one missed day. Tell yourself, “I’ll get back on track tomorrow.” Consistency matters, but perfection is not the goal.
  • Mistake 3: Comparing Yourself to Others. The gym is full of people at different stages. Use a perceived exertion scale rather than comparing your speed or weight to the person next to you. Run your own race.
  • Mistake 4: Choosing Intensity Over Enjoyment. If you hate running, don’t run. You won’t stick with something you dread. The best exercise is the one you genuinely enjoy. Find that and do it.
  • Mistake 5: Expecting a Miracle Cure. Exercise will help, but it’s not a magic pill that erases all your problems. Some days will still be hard. That’s normal and doesn’t mean exercise isn’t working.
  • Mistake 6: Ignoring Your Body’s Signals. Pushing through severe pain or exhaustion is counterproductive. It can lead to injury or cause you to resent the habit. Learn the difference between comfortable discomfort and true pain, and always rest when you need to.

When Exercise Isn’t Enough: Red Flags and Next Steps

Exercise is a powerful tool, but it’s not a replacement for professional help. You need to know the difference between struggling on a hard day and needing clinical intervention.

Red Flags to Watch For

If you or someone you care about is experiencing any of the following, it’s time to seek professional help, regardless of your exercise routine:

  • Suicidal thoughts or self-harm thoughts.
  • Symptoms that are worsening, not improving, despite lifestyle changes.
  • An inability to function at work, school, or in relationships.
  • Depression or anxiety that lasts more than two weeks and feels unshakable.
  • Rapid mood swings or impulsive, risky behavior.

What to Do

Your first stop should be your primary care physician. They can rule out any underlying medical conditions and give you a referral to a licensed therapist or psychiatrist. Psychotherapy, particularly Cognitive Behavioral Therapy (CBT), has a strong evidence base for treating depression and anxiety.

Here’s the key insight: exercise is not either-or. It can work alongside therapy and medication to improve your outcomes. Many people find that adding exercise supports their treatment rather than replacing it.

Think of exercise as one leg of a three-legged stool, with therapy and medication as the other two. Remove one, and the whole structure gets shaky. This approach gives you the strongest chance of recovery and long-term stability.